UPDATE: Our mapping wizard Richard has produced this super little tool to answer any questions you might have about SFI26: https://sfi26.soilbenchmark.com/
📊🚜 DEFRA has finally published the detail on SFI26:
My take (comparing it to the latest take-up data I've been tracking 🤓): this looks like a pretty sensible reset if the main goal is to spread the budget across more farms.

It’s a clear shift in approach:
👉 less money for paperwork
👉 lower rates on some of the most expensive actions
👉 more focus on caps / access / value for money
TL;DR
📌 71 actions (down from 102)
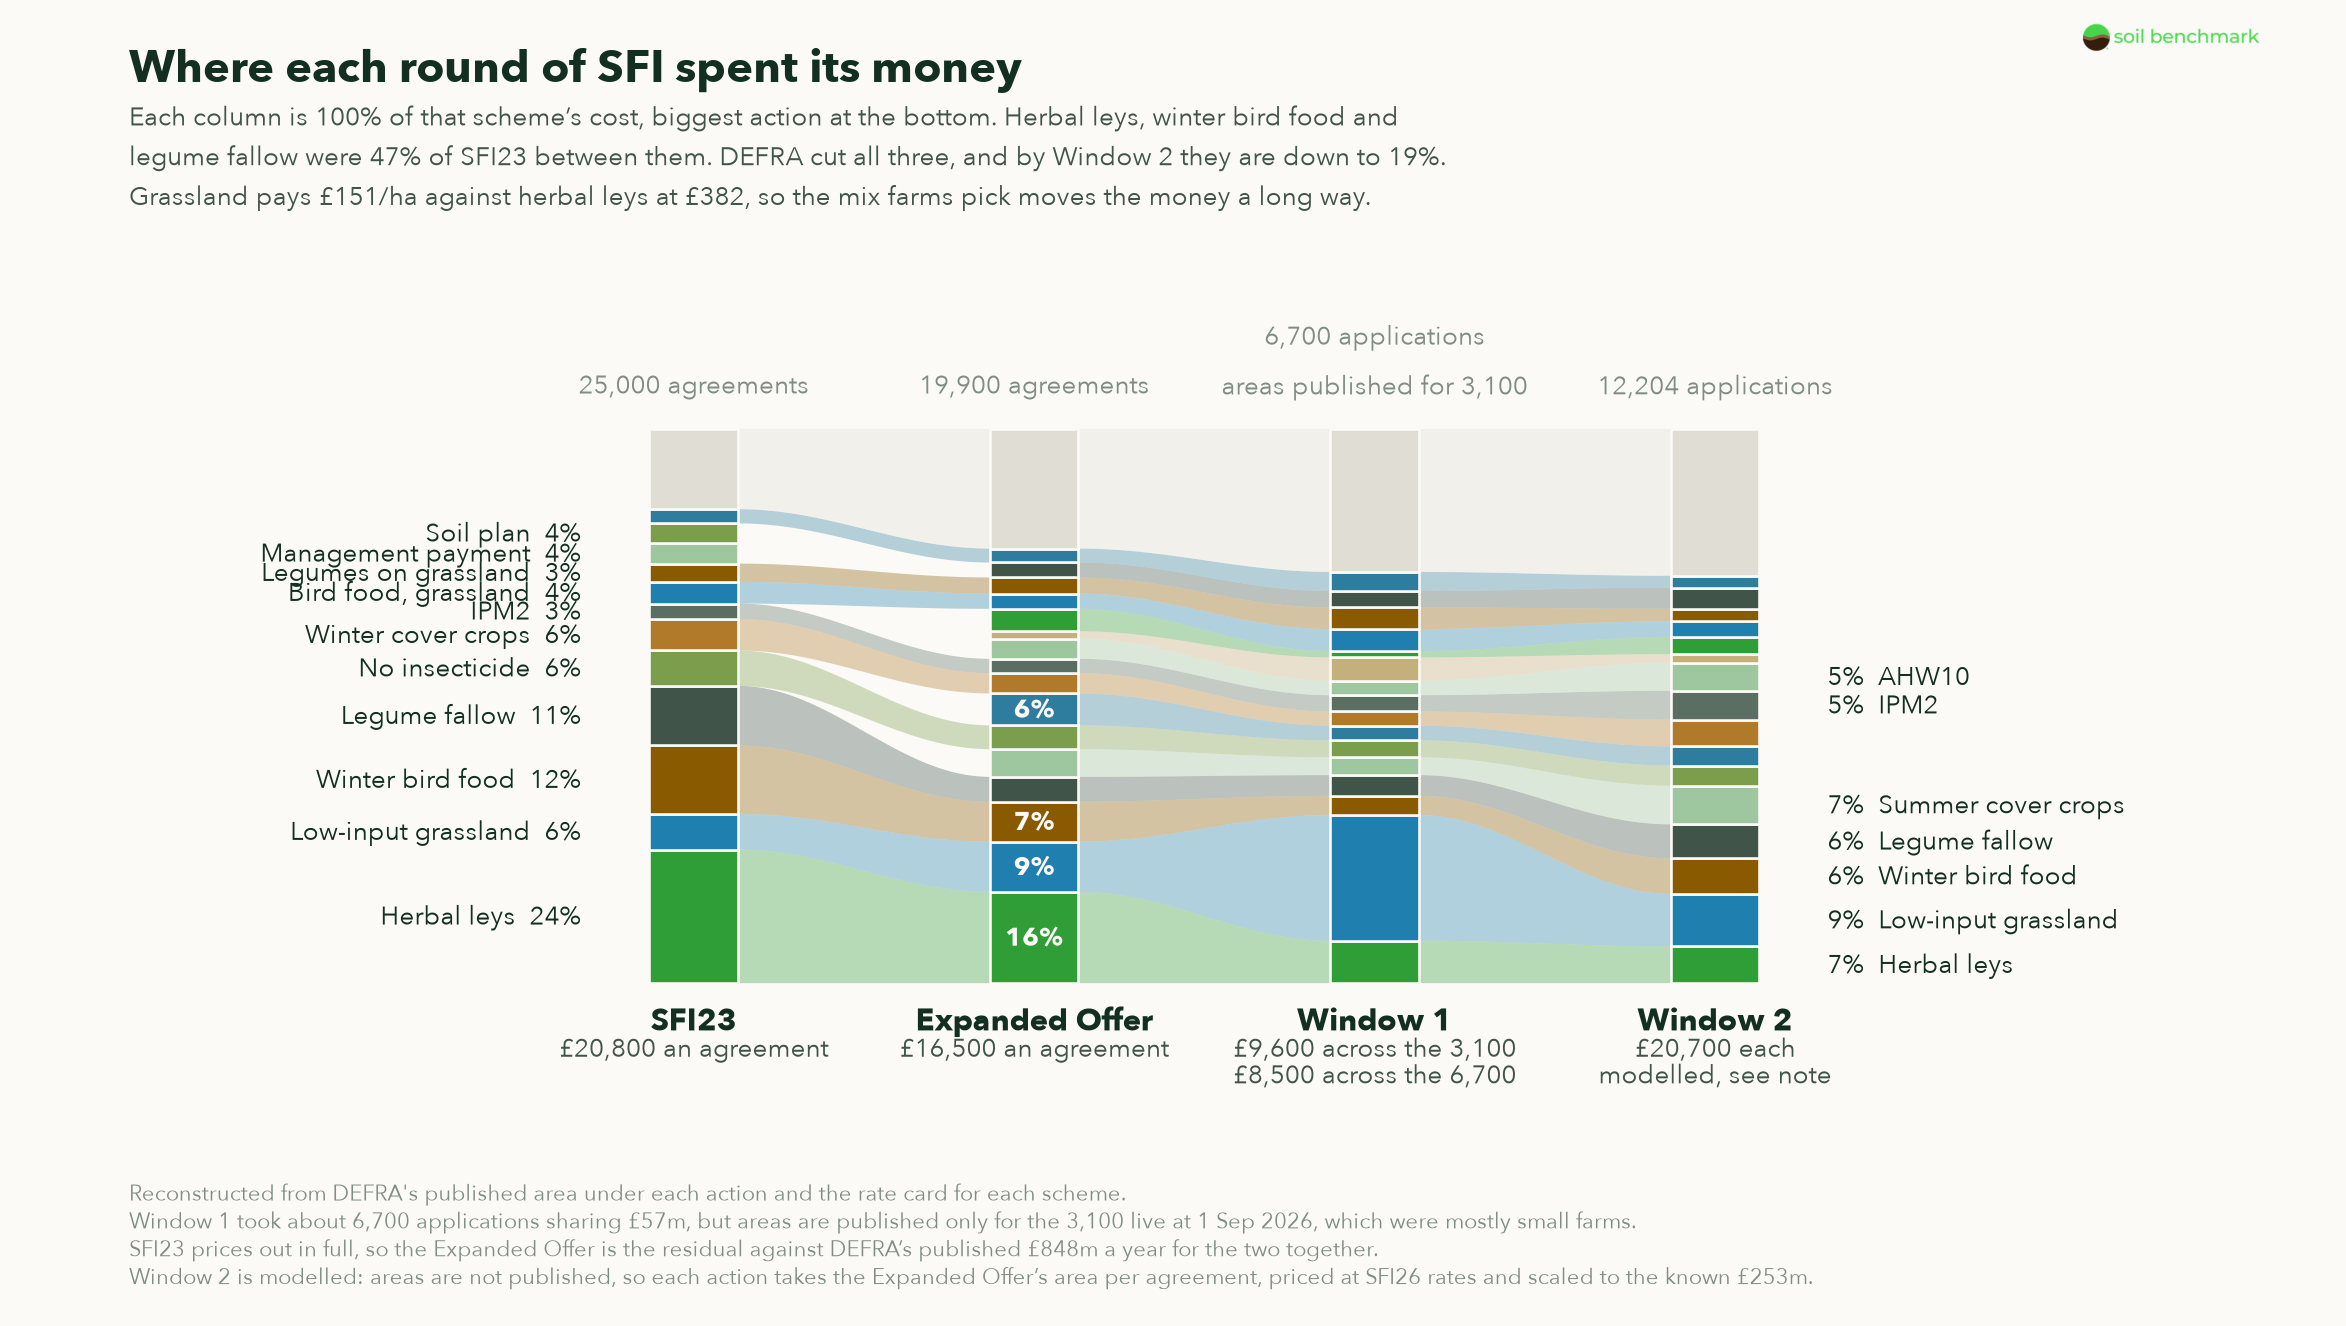
Rates cut for SAM3 / AHL2 / NUM3
Management payment & 5 planning actions removed
1st window for 3-50ha farms
£100k cap
1) DEFRA has gone straight after the expensive actions
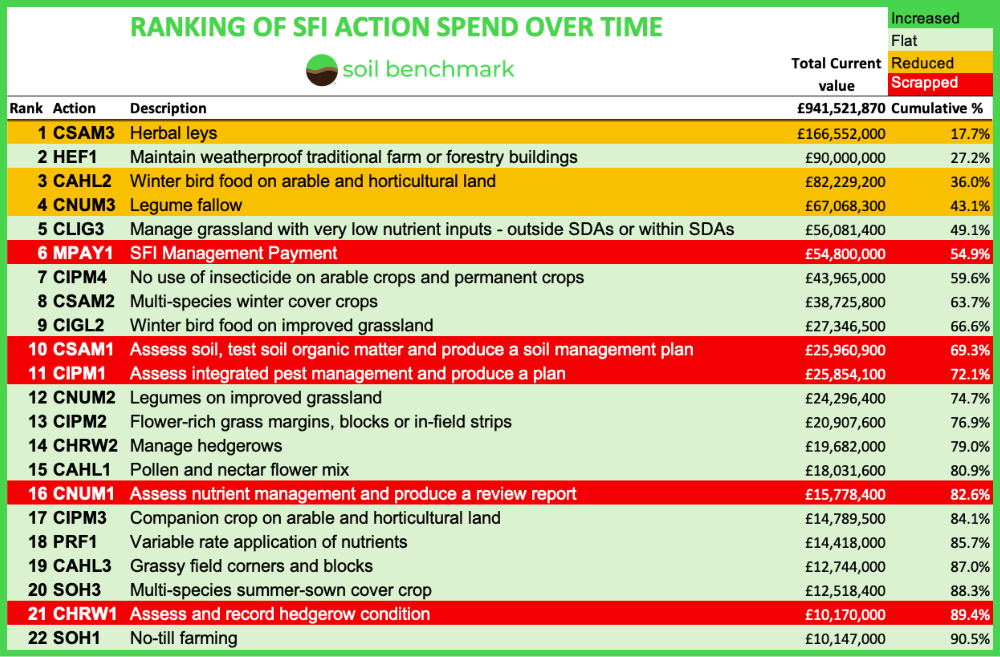
💰Using latest SFI take-up figures (to Nov), the 3 reduced-rate actions (SAM3, AHL2, NUM3) were worth £316m/yr combined. That’s more than ⅓ total annual SFI cost (£942m).

At the new rates, those same 3 actions would pay £96m less = saving 10% of the budget.

2) Simplification: mostly sensible ✂️
Around ⅔ of removed actions were in fewer than 100 agreements each (vs SAM1 used in 27,700!)

One oddity: HEF1 (maintain trad. farm buildings) is only on 80ha, but at £5/sqm it adds up to £90m! Feels a strange one to keep if the stated focus is environmental outcomes 🤷
3) Biggest shift in approach: 😵 plans 📝
Removing management payment + the 5 planning actions saves £135m/yr (14% of budget).Some of that is understandable - IPM1 became very tick-box.
But there’s a missed opportunity I think. The value in these plans wasn't the document itself. It was using the plan to start better conversations.
That’s the bit they were trying to get at: mindset shift.
So if not plans, then what replaces that?
👉 more enforcement?
👉 easier tools?
👉 more advisor support?
👉 farmer groups?
This is exactly the territory of my Nuffield work (linktr.ee/tscrope) so I’ll be watching the new £30m Farmer Collaboration Fund closely.
4) Access / fairness: probably more farms get in 🤝
The cap + rate cuts + removals should definitely mean more farms can access SFI (hard to quantify exactly yet).
But scrapping the management payment will hit smaller farms hardest.
5) What it means for us at Soil Benchmark 🪱💻
SAM1 was a big part of how we've got to 1.2m ha on the platform in a little over 2 years (30% of SAM1 area).

First the SFI pause, and now this, has definitely made us grateful we didn’t just rest on our laurels with SAM1 and instead followed what customers were asking for next:
💩 manure spreading maps
🗺️ NVZ plans
🧪 nutrient management
🐛 NEW: spray recommendations
😅 phew.
And with the disruption in the UK agronomy software market right now, we’ve (again) got lucky with timing.
6) Overall verdict
Access ✅
Simplification ✅
Environmental impact❓
The key test is how much lower rates on the big actions reduce uptake (and so environmental delivery overall)
Key questions now 🧭
💷 Budgets?
🤔 What replaces the role the management plans were trying to support in terms of mindset shift?
Keen to get your take👇